News
BMRI’s bond issue: Himbara’s government financing under scrutiny
Tenggara Strategics October 21, 2026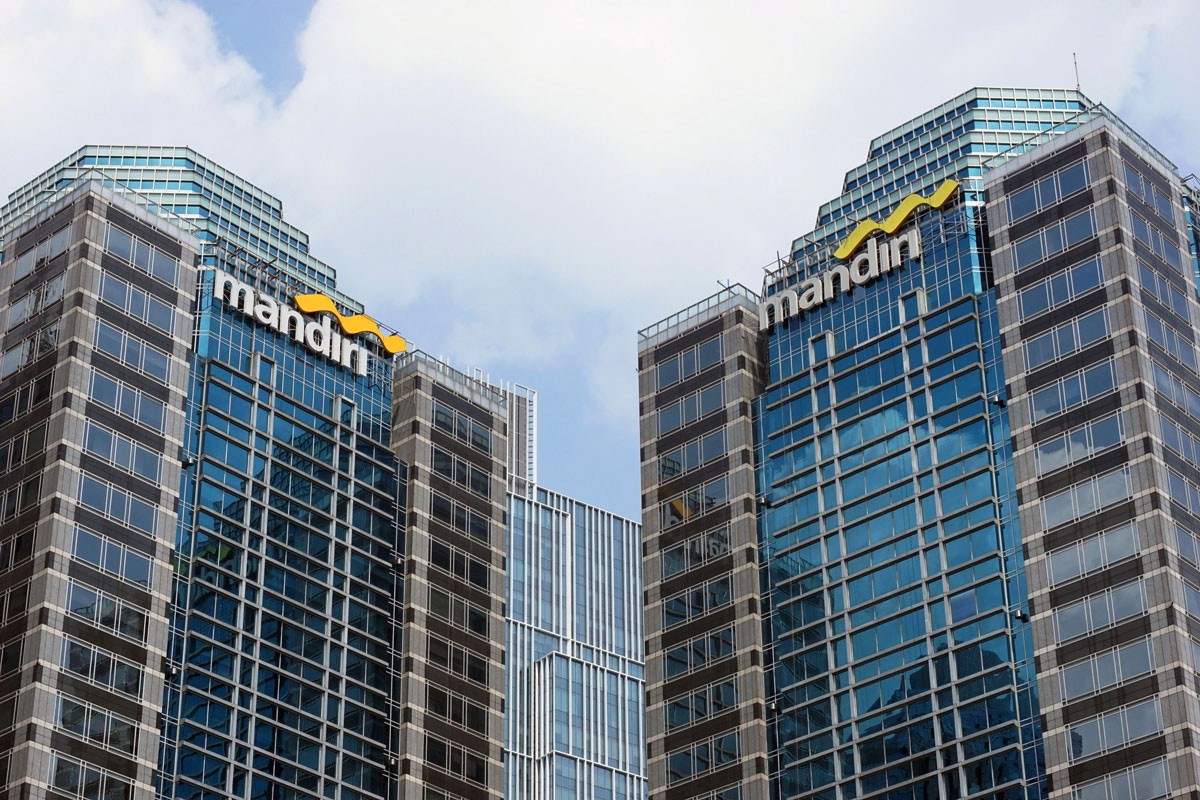 State-owned Bank Mandiri buildings in Jakarta pictured in this undated file photo. (Courtesy of Bank Mandiri)
State-owned lender Bank Mandiri (BMRI) recently issued US$750 million in perpetual bonds, an uncommon instrument among Indonesian corporates, with an initial annual distribution rate of 7.35 percent. The issuance is intended to strengthen the bank’s capital base by bolstering its Additional Tier 1 (AT1) capital and supporting business expansion. However, it has also fuelled speculation that BMRI, along with other Himbara banks, may be facing mounting financial demands from their involvement in financing government programmes.
The initial distribution rate is notably higher than yields on conventional US-dollar corporate bonds with comparable credit ratings, which have generally ranged between 5 and 5.5 percent, according to fixed-income analysts. For comparison, Danantara’s five-year United States dollar bonds issued last year carried a distribution rate of 5.35 percent. The higher rate may reflect the additional risks associated with perpetual bonds, particularly the absence of a fixed maturity date, which leaves investors without a predetermined date for recovering their principal.
Concerns over BMRI’s capital position add to questions about the financial demands facing the bank. In June 2026, its capital adequacy ratio (CAR) stood at 17.52 percent, among the lowest of Indonesia’s Category IV Commercial Banks by Core Capital (KBMI IV). By comparison, BNI’s CAR was 18.1 percent, while BRI and BCA reported ratios of 21.5 percent and 26.79 percent, respectively.
The government’s growing reliance on Himbara banks to finance its flagship programmes provides important context for these concerns. One of the largest commitments involves the Red and White Cooperatives initiative, under which state-owned Agrinas Pangan Nusantara borrowed Rp 240 trillion (US$13.4 billion) from Himbara banks to finance the construction of village cooperatives. The loans are scheduled to be repaid over six years, requiring annual installments of Rp40 trillion.
The first instalment, due on Sept. 25, 2026, has faced delays despite the government having set aside the necessary funds. By Oct. 7, the Finance Ministry had deposited approximately Rp 37 trillion into escrow accounts at Himbara banks, but the funds could not yet be released as loan repayments pending the verification and validation of the cooperatives and the completion of the required administrative procedures. The delay highlights how procedural bottlenecks in a government-backed financing scheme can affect repayment timelines and potentially expose participating banks to additional credit risk.
Himbara banks have also been involved in the government’s free nutritious meal program, including by financing the construction of kitchens operated by programme service providers. In November 2025, the National Nutrition Agency, Danantara and Himbara banks signed an agreement to facilitate such financing.
BMRI’s own capital and risk exposure reports show that its risk-weighted assets (RWA) have been growing rapidly. In June 2026, RWA reached Rp 1,399.4 trillion, up 13.1 percent year-on-year from Rp 1,237.7 trillion. Over the same period, the bank’s CAR declined from 18.35 percent to 17.52 percent, a drop of 0.83 percentage points. The divergence suggests that regulatory capital has not kept pace with the growth in risk-weighted assets, narrowing the bank’s capital buffer relative to its risk exposure. While this trend does not, by itself, establish that government-directed lending is responsible for the deterioration, it underscores the importance of assessing how the bank’s expanding financing commitments affect its capital position.
Nevertheless, BMRI’s decision to issue perpetual bonds does not necessarily indicate that the bank is experiencing serious financial distress. The 7.35 percent distribution rate must be considered in light of the instrument’s structure and risk profile. BMRI’s perpetual bonds are subordinated and non-cumulative: they rank below senior debt in the event of insolvency, while cancelled distributions do not accumulate for future payment. They also have no fixed maturity date, meaning investors have no predetermined date on which they can expect their principal to be repaid. These features expose investors to greater risks than conventional corporate bonds and help explain the higher return required to attract buyers. Although perpetual bonds remain relatively uncommon in Indonesia’s banking sector, BMRI is not the first domestic bank to issue AT1 capital securities.
Even if BMRI is not facing immediate financial distress, the issuance raises broader questions about the government’s reliance on large state-owned banks to finance its programmes. Concerns about placing too much of this burden on Himbara banks have been raised repeatedly, yet the practice continues. The government could reduce the concentration of financing demands by diversifying its funding sources while ensuring that state-owned banks retain sufficient capital to support their commercial operations and withstand potential losses. The warning signs may not point to an immediate crisis, but waiting until capital buffers come under severe pressure would leave policymakers with far less room to manoeuvre.
Related Articles